Yes, it’s possible to get a mortgage without a traditional credit score.
If you’ve chosen to live without debt and have a 0 credit score, Churchill Mortgage can help you explore home loan options that look more in depth into your payment history than a traditional credit score.
Having no credit score generally means there isn’t enough recent information in the traditional credit reporting systems to calculate a score. That’s different from having a low credit score caused by missed payments or other credit issues.
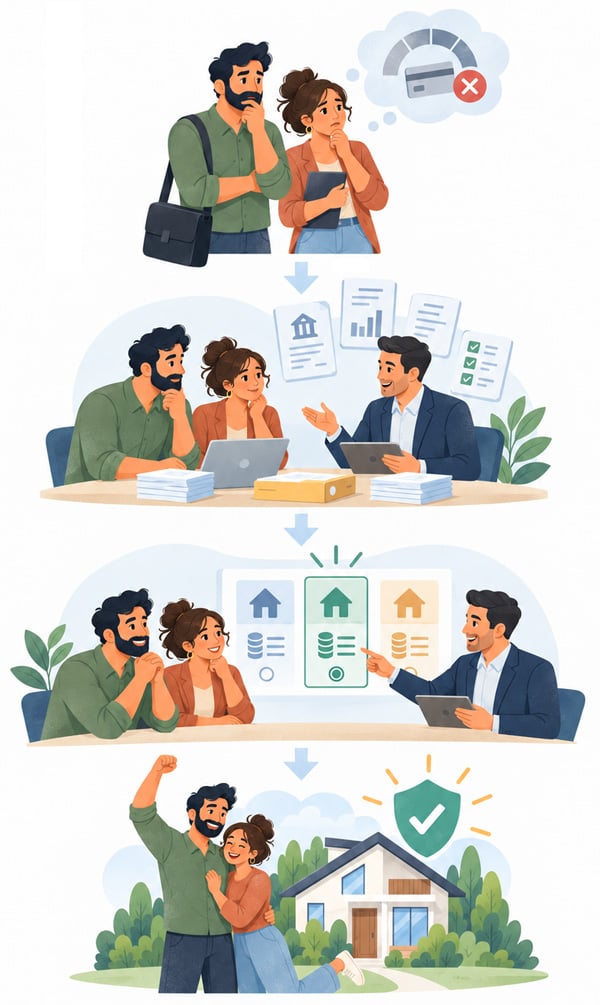
How to Get a Mortgage Without a Credit Score
1. Talk with a Home Loan Specialist
Start by discussing your situation with a Churchill Loan Officer.
2. Document income, assets, and payment history
Gather documents with income, assets, and payment history for manual underwriting.
3. Determine eligible loan options
Find the right loan, program, and options that fit your needs based on your details.
4. Get approved and shop for your home
Once approved, it's time to start the fun part - shopping for your new home!
Ready for your first step?Complete the form to get connected with a Churchill Home Loan Specialist today.
Frequently Asked Questions
Can I buy a house without a credit score?
Yes, it may be possible to buy a house without a traditional credit score. Through manual underwriting, a lender can review your overall financial history including consistent payments for rent, utilities, insurance and other recurring expenses, instead of relying solely on a credit score.
Having no credit score is different from having a low credit score. Churchill Mortgage specializes in helping debt-free and credit-invisible home buyers explore no-score mortgage options. A Churchill Home Loan Specialist can review your financial picture and help you understand which loan programs may be available to you.
Can I get a mortgage if I don’t use credit cards?
Yes. Not using credit cards does not automatically prevent you from getting a mortgage. If you have little or no traditional credit history, a lender may use manual underwriting to review other signs of financial responsibility, such as your rent, utilities, insurance and other recurring payments.
Churchill Mortgage specializes in helping debt-free and no-credit-score home buyers explore their mortgage options. A Churchill Home Loan Specialist can review your financial history and help you understand what documentation and loan programs may be available.
What is manual underwriting?
Manual underwriting is a process in which a mortgage underwriter personally reviews your financial history instead of relying primarily on an automated system or credit score. The underwriter may evaluate your income, employment, savings, debts and payment history for expenses such as rent, utilities and insurance.
This process can help borrowers who have no traditional credit score demonstrate how they manage their finances. Churchill Mortgage has extensive experience with manual underwriting and can help you understand the documentation needed to explore your no-score mortgage options.
What is the difference between no credit and bad credit?
A low credit score means you have enough reported credit activity to generate a score, but factors such as late payments, high balances, or other credit issues may have lowered it. No creditscore (credit invisible) generally means there is not enough recent credit activity to calculate one. It does not necessarily mean you have poor credit.
If you have a credit score of zero (0) because you avoid debt or do not use traditional credit, manual underwriting may allow a lender to evaluate other payment history. Churchill Mortgage specializes in helping no-score home buyers explore mortgage options based on their broader financial picture.
Do I need to build credit before buying a house?
Not necessarily. If you do not have a credit score because you avoid debt or do not use credit cards, you may be able to qualify for a mortgage through manual underwriting. This process considers other parts of your financial history, including income, savings, and consistent payments for expenses such as rent, utilities, and insurance.
Before opening a credit card or taking on debt to build a credit score, talk with a Churchill Mortgage Home Loan Specialist. Churchill specializes in no-score mortgages and can help you explore your options without assuming you need traditional credit first.
What payments or bills can be used for manual underwriting?
An underwriter may use consistent payments from non-traditional credit sources to evaluate how you manage your financial obligations. Examples may include:
Rent or housing payments
Utilities, internet, and phone bills
Auto, renters, homeowners, medical, or life insurance
Childcare or school tuition
Payments to local retail or furniture stores
Payments for rented vehicles or other durable goods
Medical bill payments
A consistent savings history
Borrowers may need at least four sources showing 12 months of consistent payment history. However, documentation requirements can vary based on the loan program and your financial situation. A Churchill Home Loan Specialist can help you determine which records may qualify.

 Secure Form
 Takes 1 Min
 See Your Options